Master Seller Concessions
Master Seller Concessions
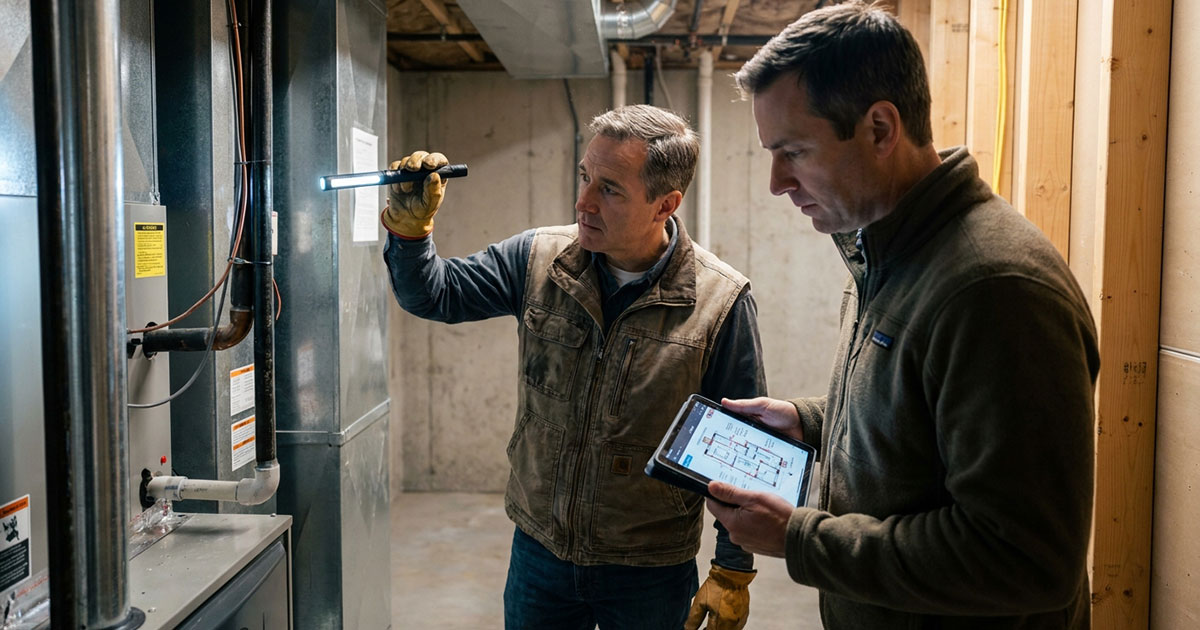
With nearly forty-five percent of property sales closing with seller concessions, today’s buyers hold unprecedented negotiating leverage. Rising inventory and elevated mortgage rates have shifted power balances across the country. Understanding how to request closing fee coverage, temporary rate buydowns, and repair credits enables buyers to dramatically lower upfront costs and secure long-term financial relief.
The Power Shift
Today’s real estate environment marks a profound transformation in negotiating dynamics as market conditions tilt back toward purchasers. For years, purchasers faced fierce competition, waiving vital protections and bidding far over asking prices simply to secure a home. That frantic pace has cooled significantly under the pressure of higher mortgage borrowing costs, expanding listing inventories, and longer average marketing timelines. Properties that once sparked instant bidding wars now linger on local MLS portals for weeks, forcing homeowners to confront an increasingly cautious buyer pool. In this recalibrated landscape, roughly forty-five percent of completed residential transactions now feature tangible seller concessions. These financial allowances demonstrate that homeowners are increasingly eager to keep transactions alive rather than risk watching their properties stagnate indefinitely. For prospective buyers entering negotiations, this statistical trend is not merely an interesting industry data point, but rather a direct mandate to demand substantial financial assistance before signing any final purchase contract.
Target Closing Costs
Rather than fixating entirely on knocking down the nominal listing price, sophisticated purchasers prioritize direct assistance with out-of-pocket settlement expenses. Many buyers exhaust substantial portions of their liquid cash reserves assembling the down payment, leaving them vulnerable to substantial lender fees, transfer taxes, title policies, and municipal recording charges due on closing day. Requesting that the selling party fund these mandatory transaction expenses immediately preserves precious capital that can remain safely cushioned in private emergency savings accounts. When structured carefully within regulatory lender limitations, standard residential mortgages permit sellers to contribute several percentage points of the total loan valuation directly toward customary buyer closing costs. For someone purchasing an average single-family home, this approach can easily keep ten to fifteen thousand dollars in cash reserves while keeping monthly payments virtually identical to an unassisted lower-price scenario. Framing this request as a necessary condition for mutual contract ratification allows the seller to maintain their headline sales figure while solving the primary financial hurdle standing between the buyer and a ratified deal.
Lower Your Rate
Persistent mortgage rates hovering around seven percent have fundamentally eroded traditional purchasing power, making creative financing concessions far more valuable than simple headline discounts. The most powerful concession mechanism in the modern housing market is the seller-funded temporary interest rate buydown, often structured as a two-one buydown arrangement. In this framework, the listing party deposits an upfront cash credit into an escrow reserve account at closing, which subsidizes the borrower’s monthly mortgage payments by two full percentage points during the initial twelve months and one percentage point throughout the second year. To achieve an equivalent monthly cash-flow savings through a conventional price reduction, a buyer would have to convince a seller to slash fifty or sixty thousand dollars off the listing price, which almost always triggers an outright rejection. By contrast, funding a two-year buydown typically costs the seller only a fraction of that amount, making it an extraordinarily appealing compromise that protects the homeowner’s net proceeds while delivering profound monthly payment relief to the buyer when it matters most.
Leverage the Inspection
Professional property inspections provide buyers with critical leverage to extract meaningful financial concessions just as the transaction enters its most delicate phase. Once a home enters pending status, the seller becomes psychologically committed to moving forward, making the prospect of a cancelled contract and an embarrassing return to the public market deeply unattractive. When the comprehensive physical evaluation inevitably reveals deferred maintenance, aging HVAC systems, deteriorated roof flashing, or electrical shortcomings, the purchaser must resist the temptation to demand physical contractor repairs by the homeowner. Requesting physical fixes often results in rushed, low-cost patch jobs handled by the seller’s cheapest chosen vendors, whereas demanding an equivalent closing credit leaves quality control entirely in the buyer’s hands. By presenting documented contractor estimates directly alongside the detailed inspector findings, buyers establish an objective basis for requesting substantial repair credits. Sellers readily understand that these newly uncovered defects now constitute mandatory disclosures for any future prospective buyer, making a cash credit at closing the fastest, cleanest, and most pragmatic route to finalizing the escrow process.
Strategic Negotiation
Unlocking maximum concessions requires meticulous timing, clear market evidence, and an understanding of the individual seller’s personal urgency. Attempting aggressive concession demands on a meticulously updated property during its very first weekend of open-house showings rarely yields favorable outcomes, as listing agents usually counsel their clients to wait for competing proposals. Instead, the greatest bargaining leverage emerges once a listing surpasses the thirty-day threshold without securing a ratified purchase agreement, or immediately after a previous buyer’s financing collapsed. Before drafting an offer, collaborating closely with an experienced buyer agent to analyze local neighborhood inventory metrics, recent comparable sales concessions, and the seller’s specific moving timeline reveals the exact pressure points to target. Packaging the concession request within an otherwise clean, uncomplicated offer that features prompt inspection deadlines and rock-solid financing pre-approvals significantly softens the impact of asking for seller funds. When homeowners perceive that agreeing to financial credits guarantees an expedient, trouble-free path toward a completed closing, they will routinely absorb significant transaction expenses to get the deal across the finish line.
John Doe
State of Alabama
122 Commerce St, Montgomery AL 36104
Email: service.myre@gmail.com
Phone: (555) 555-55-55
I take the time to listen carefully to understand my client’s needs, wants and concerns. I will be ready to take quick action when required and spend more time with those who aren’t quite sure which direction to take. My genuine concern for my client’s best interests and happiness ensures the job is done!